
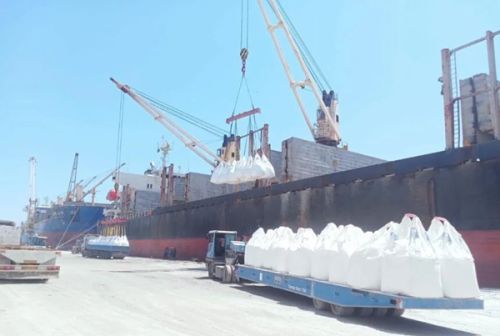
France’s dependence on North African fertiliser producers has come under renewed scrutiny following reports that Algeria asked its urea manufacturers to suspend shipments to the French market.
Egypt and Algeria supplied nearly 60 per cent of France’s urea imports in 2025, exporting 631,031 tonnes and 480,989 tonnes respectively, according to international trade data.
Reuters reported on October 23, 2026, citing diplomatic and industry sources, that Algeria had requested a suspension of urea shipments to France. However, no official announcement had been made at the time, while France’s Foreign Ministry said it had received no formal notification.
The potential restriction has raised questions about the security of France’s fertiliser supply and the extent to which alternative producers could make up for any disruption.
Urea, a nitrogen-based fertiliser, is widely used in agriculture to improve crop growth and productivity.
Egypt and Algeria Dominate French Urea Imports
Customs data published through UN Comtrade and accessed via the World Bank’s World Integrated Trade Solution platform show that Egypt and Algeria were among France’s largest urea suppliers in 2025.
French imports from Egypt rose by 25 per cent compared with 2024, while purchases from Algeria increased by 11.3 per cent.
Both countries have established fertiliser industries supported by access to natural gas, a key raw material in the production of ammonia and urea.
Egypt’s annual urea production capacity is estimated at between seven million and 7.3 million tonnes, according to the American Chamber of Commerce in Egypt. Major producers include MOPCO, Abu Qir Fertilizers, KIMA and Alexfert.
Egypt’s Ministry of Petroleum and Mineral Resources reported that MOPCO produced 1.718 million tonnes of urea in 2024, exporting 947,000 tonnes. Europe accounted for 89 per cent of those exports.
In Algeria, Sorfert, which is 51 per cent owned by UAE-based Fertiglobe, has an annual production capacity of 1.3 million tonnes of urea and 803,000 tonnes of merchant ammonia.
Its Arzew facility benefits from access to export terminals at the ports of Arzew and Bethioua, giving the company direct access to international markets.
Natural Gas Costs Give North African Producers an Advantage
Natural gas plays a central role in determining the cost of producing nitrogen fertilisers because it is used to manufacture ammonia, the main intermediate product in urea production.
In a 2024 presentation, Fertiglobe highlighted its long-term gas supply agreements with Egypt’s Egyptian General Petroleum Corporation and Algeria’s Sonatrach. The company said favourable gas supply terms, competitive production costs and proximity to export ports strengthened its position in international markets.
Currency movements have also improved the competitiveness of Egyptian exports. The depreciation of the Egyptian pound has made products from the country more attractive to international buyers, according to France’s Treasury Directorate General.
French imports of Egyptian fertilisers and nitrogen compounds reached €284 million in 2025, representing a 38 per cent increase from the previous year. However, the figure covers a broader category of products beyond urea alone.
European manufacturers, meanwhile, continue to face pressure from high energy costs.
The European Commission’s Fertiliser Action Plan, published in May 2026, estimated that natural gas accounts for between 70 and 80 per cent of the production costs of nitrogen fertilisers in Europe.
The Commission also reported that facilities representing nine per cent of Europe’s ammonia production capacity had permanently closed since 2023, reflecting the impact of high gas prices and difficult operating conditions.
Nigeria and Other Suppliers Could Face Increased Demand
Any prolonged disruption to Algerian shipments could force French importers to seek alternative sources of supply.
The Netherlands, Belgium and Nigeria are among France’s other urea suppliers. However, their existing export volumes raise questions about how quickly they could compensate for a significant reduction in Algerian deliveries.
France imported approximately 48,000 tonnes of urea from Nigeria in 2025, considerably below the volumes received from Egypt and Algeria.
The ability of alternative suppliers to increase exports will therefore be an important factor in determining how France responds to any disruption.
EU Policies Add to Pressure on Fertiliser Imports
France’s longer-term dependence on imported fertilisers will also be influenced by efforts to strengthen European production.
The European Commission’s Fertiliser Action Plan, introduced in May 2026, includes measures aimed at supporting manufacturers and reducing the European Union’s reliance on external suppliers.
The industry is also adjusting to the European Union’s Carbon Border Adjustment Mechanism (CBAM), which entered its definitive phase on January 1, 2026, bringing new carbon-related requirements for importers of covered products, including fertilisers.
Ultimately, France’s ability to diversify its urea supply will depend on several factors, including European energy prices, the impact of CBAM, the availability of alternative exporters and the capacity of competing producers to increase shipments.
The reported Algerian move has therefore highlighted a broader challenge for France: maintaining a reliable fertiliser supply while navigating energy-market pressures and changing trade policies.